The corporate tax rules in the UAE have really shifted since the new law (Federal Decree-Law No. 47 of 2022) for taxing companies started. For UAE businesses in Free Zones, it’s super important to know the difference between “qualifying” and “excluded” activities. This is because that difference decides if your company gets the attractive 0% corporate tax rate. Let’s understand what are the qualifying activities for corporate tax in UAE:
So, What Exactly is a Qualifying Free Zone Person (QFZP)?
A Qualifying Free Zone Person (QFZP) is basically a company set up in a UAE Free Zone. It has to meet certain rules under the Corporate Tax Law so it can pay 0% tax on the money it earns from activities that “qualify.” To keep this status, a business needs to:
- Mostly earn money from activities that count as “qualifying income in UAE”
- Follow the “de minimis” rule – meaning income that doesn’t “qualify” can’t be more than AED 5,000,000* or 5% of its total earnings, whichever amount is smaller
- Keep proper audited financial records, as laid out in Ministerial Decision No. 84 of 2025
- Show it has a real presence within the Free Zone
If a company doesn’t meet even one of these conditions, it loses its QFZP status for that whole tax period.
Here’s the Complete List Of Activities That Qualify
According to Ministerial Decision No. 229 of 2025, these are the qualifying activities for corporate tax in UAE:
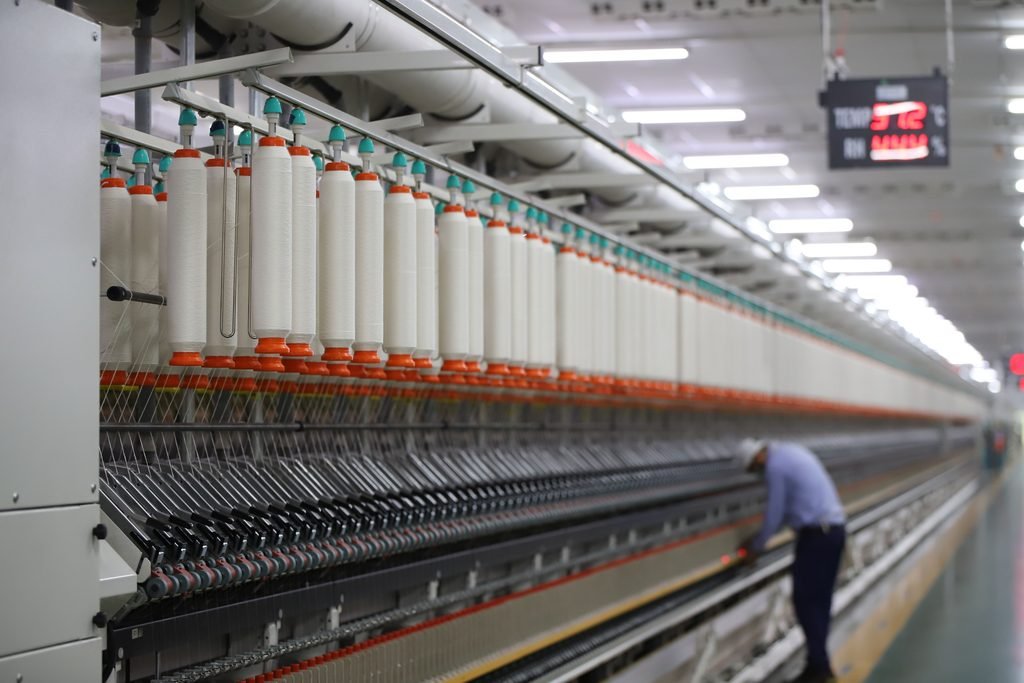
1. Manufacturing and Processing
Activities for the free zone include taking or putting together products – from raw materials all the way to finished goods. This also covers any extra processing done in a Free Zone or Designated Zone that adds value.
2. Trading of Qualifying Commodities
A big change in MD 229 is that they’ve made the definition of “qualifying commodities” much wider. This now covers things like metals, minerals, industrial chemicals, related by-products, energy products, farm goods, and even environmental items like carbon credits and certificates for renewable energy.
What’s really key is that they’ve dropped the rule about these commodities having to be actively traded on a stock exchange. Now, it’s enough if there’s a listed price, whether it’s on an exchange or reported by a Recognized Price Reporting Agency (RPRA) mentioned in Ministerial Decision No. 230 of 2025.
3. Holding of Shares and Securities
Money you make from holding shares and other investments – like dividends, profits from selling assets, or profit payouts – counts, as long as you meet the Corporate Tax Law’s conditions.
4. Treasury and Financing Activities
A QFZP can now handle its own treasury and financing, or do it for “Related Parties,” which is a big step up from before when it only covered “Related Parties.” This wider scope fits with what the Federal Tax Authority (FTA) had hinted at earlier, and now it’s officially in the law.
5. Reinsurance Services
Offering reinsurance services falls into the qualifying income under UAE corporate tax. But regular banking and most insurance activities don’t count – they’re “excluded.” So this specific allowance for reinsurance is really important for companies in finance.
6. Fund Management Services
Running investment funds and giving related services to financial companies that are regulated also counts. This helps the UAE become a major center for managing money and assets.
7. Wealth and Investment Management Services
Businesses operating within the UAE offering services like managing investment portfolios and giving wealth advice to clients, especially when done through licensed companies, are also on the qualifying list for corporate tax compliance.
8. Headquarter Services to Related Parties
Businesses operating within free zones or mainland, giving management, admin, coordination, or strategic advice services to companies in the same group counts. This is a huge plus for regional holding companies and the main offices of international groups.
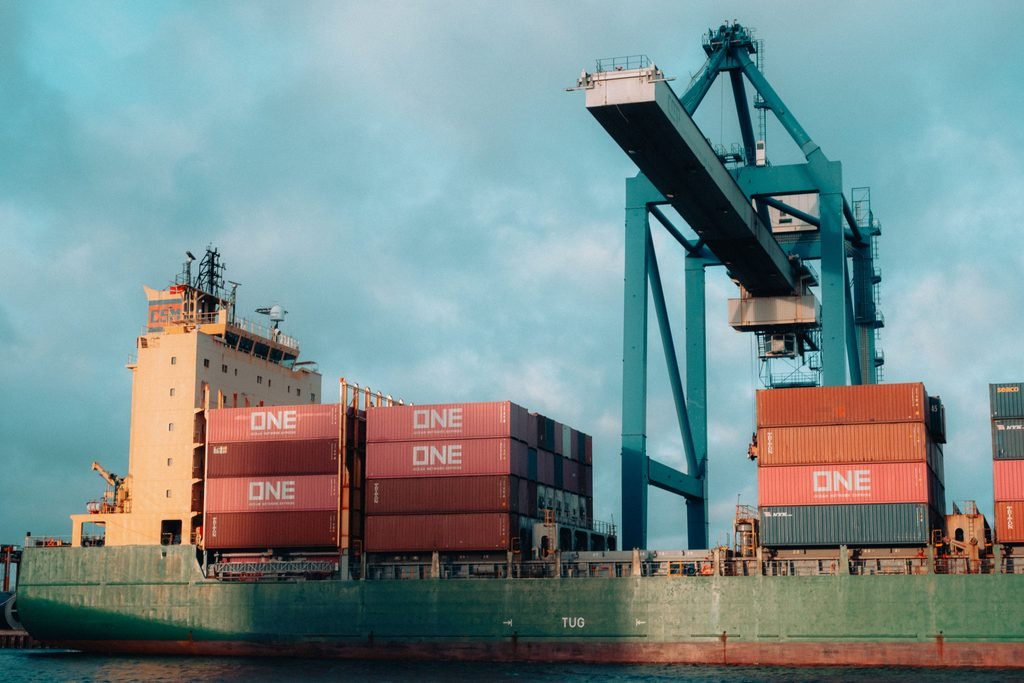
9. Logistics Services
Offering transport, storage, and logistics help from inside a Free Zone or Designated Zone is also a qualifying activity for taxable income. These activities defined under the UAE show how important the UAE is as a global hub for logistics.
10. Distribution of Goods or Materials in or from a Designated Zone
This counts when goods come into a Designated Zone and are then given to customers who will resell, process, or change them. It also now covers public benefit entities, which is new for MD 229. However, selling packaged consumer goods directly to shoppers is clearly out.
11. Ship Operations
Operating ships – including commercial shipping and chartering – counts, fitting with the UAE’s goals for its sea industry.
12. Aircraft Leasing and Related Services
Leasing out aircraft and offering maintenance or support for aviation assets is also on the qualifying list.
13. Ancillary Activities
Activities that are directly linked to any of the above qualifying ones can also count, as long as they support the main activity and aren’t just their own separate business.
Which Excluded Activities Don’t Qualify?
It’s just as important to know which activities are excluded so you can follow the rules, meaning the non-qualifying income. These activities won’t get the 0% rate:
- Dealing with individuals, unless it’s clearly part of a qualifying activity
- Banking and most insurance services (except for reinsurance)
- Finance and leasing activities that aren’t included in the qualifying list
- Owning or using property outside of commercial property in a Free Zone
- Any activities that support excluded activities
Why All This Matters for Your Company?
No matter if you trade commodities, run a regional head office, or operate a logistics company in a Free Zone, getting the rules for qualifying activities right isn’t just theory. It directly affects how much tax you pay, what audits you need, and how well you compete in the region.
The Ministry of Finance’s latest update, through Ministerial Decision No. 229 of 2025, clearly shows what they intend: the UAE wants to keep being a good place for investors and businesses.
At the same time, it’s making sure its tax rules match global transparency standards, including the OECD’s Pillar Two framework. This framework means big international companies earning over €750 million* have to pay at least a 15% effective tax rate.
Why Should You Hire Professionals?
Are you unsure about which business activities get you corporate tax benefits in the UAE?
Trying to figure out all the rules about what activities count, how Free Zones work, and what you need to do to follow the law can feel really complicated without someone experienced to help.
At Xpert Tax & Accounting, our experts help businesses figure out if they qualify, make sure they’re following all the rules, and get the best possible outcome for their corporate tax, by giving them practical advice made just for them. No matter if you’re just starting out, a small business, or a big, established company, we make things simpler. That way, you can concentrate on growing your business and know you’re completely in line with the UAE’s tax rules.
Get in touch with us today, and feel confident about the tax choices you make.
Final Thoughts
Keeping up with the newest rules for qualifying activities for corporate tax in UAE means you have to actively engage with the system. This is especially true since MD 229 goes back to June 1, 2023. Free Zone businesses should check how they classify their income, make sure their financial reports are properly audited, and get expert tax advice if they need it.
The UAE’s corporate tax system is still pretty new, but it’s becoming more complex. Knowing where your business fits into these definitions now could save you from big penalties and missing out on tax benefits later.
FAQS
Can a Company Located On The UAE Mainland Get The 0% Corporate Tax Rate For Specific Business Activities?
No, that 0% rate is only for companies set up in a UAE Free Zone that meet all the conditions to be considered a ‘qualifying Free Zone Person’.
What if a Free Zone Company Makes Money From Both Qualifying Activities And Other Activities That Don’t Qualify?
The company can still keep its Qualifying Free Zone Person status, as long as the income from non- qualifying activities for free zone companies stays below AED 5,000,000* or 5% of its total revenue, whichever of those two amounts is less, thanks to the de minimis requirements.
Is Trading Things Like Crypto Or Other Digital Assets Considered A “Qualifying Activity” for UAE Corporate Tax Purposes?
Right now, digital assets aren’t clearly mentioned as ‘qualifying commodities’ in Ministerial Decision No. 229 of 2025. So, businesses should really get professional tax advice before deciding to classify any income from these activities as qualifying.